Knowing which products generate the most revenue is not enough to understand which ones contribute most to your business’s financial success. Contribution margin helps businesses identify how much money remains from sales after covering variable costs. This information makes it easier to compare products, set prices, and decide where to focus resources.
By using contribution margin analysis, businesses can understand which products help cover fixed expenses and contribute toward operating profit.
What is Contribution Margin?
Contribution margin is the amount left from sales revenue after subtracting variable costs. These costs change with production or sales volume, such as raw materials, packaging, and sales commissions.
For example, if a product sells for $50 and its variable costs total $20, its contribution margin is $30 per unit. That $30 helps cover fixed expenses, such as rent and salaries, before contributing to profit.
A higher contribution margin can indicate that a product contributes more toward covering fixed costs, but businesses should also consider sales volume and overall demand.
Contribution Margin Formula
The contribution margin formula is straightforward:
Contribution Margin = Sales Revenue − Variable Costs
To calculate the contribution margin per unit, subtract the variable cost per unit from the selling price per unit.
For example, a company sells a product for $80 and spends $35 on variable costs. Its contribution margin is $45 per unit. If it sells 100 units, the total contribution margin is $4,500.
Understanding the formula helps businesses compare products and evaluate pricing decisions.
How to Calculate Contribution Margin
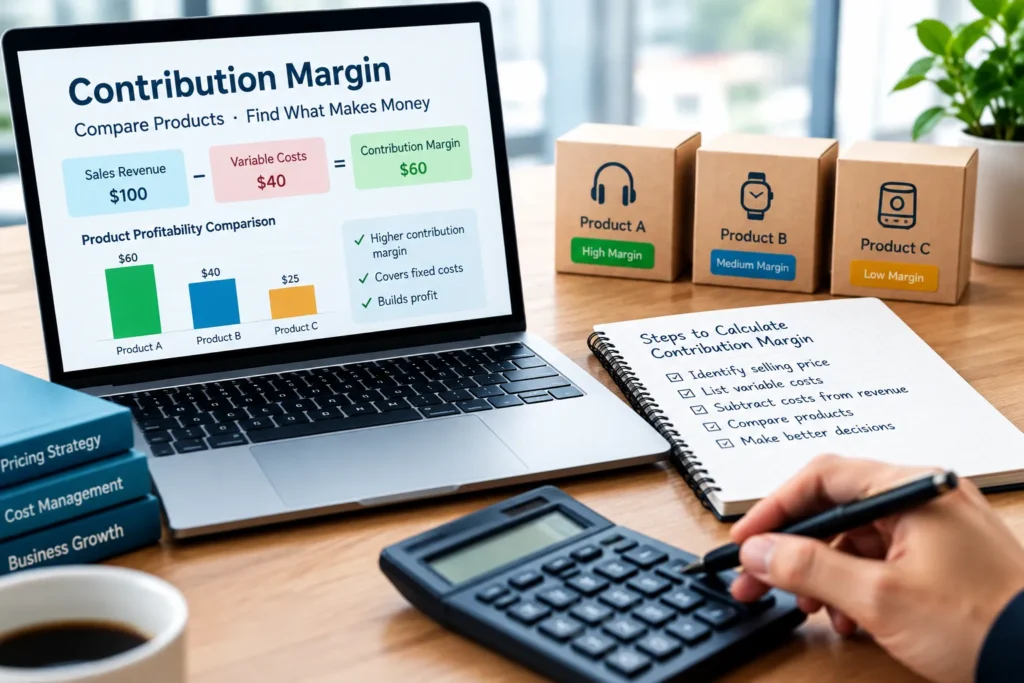
If you want to learn how to calculate contribution margin, start by identifying the selling price and all variable costs associated with the product. Include costs that rise with an increase in units produced or sold.
Subtract total variable costs from sales revenue to find the total contribution margin. If you need the margin per unit, then you need to subtract the variable cost per unit from the selling price.
Update your cost data as prices from suppliers, shipment costs, commissions, and production efficiency may change and impact the outcome.
Understanding the Contribution Margin Ratio
The contribution margin ratio shows the percentage of sales revenue remaining after variable costs.
Contribution Margin Ratio = (Contribution Margin ÷ Sales Revenue) × 100
For example, if a product generates $60 in contribution margin from $100 in sales, its ratio is 60%. This means 60 cents of every sales dollar remains after variable costs.
The ratio is useful when comparing products with different selling prices. However, a higher ratio does not automatically mean a product generates the most total contribution if its sales volume is low.
Contribution Margin vs. Profit Margin
The understanding of contribution margin vs profit margin is crucial, since both are for different purposes.
Contribution margin is sales revenue minus variable costs. It provides a clear indication of the remaining margin for paying fixed costs, and then contributing to profits.
Profit margin is a measure of profit as a percentage of revenue, excluding the expenses used in the choice of profit measure. Different costs are used in the calculation depending on the type of profit margin used by a business; gross profit margin, operating profit margin, or net profit margin.
Businesses can be better equipped with both these metrics to gain a better understanding of the financial performance of a product and the contribution at the product level.
Variable Costs and Fixed Costs
To determine the contribution margin you need to be familiar with variable costs and fixed costs. Fixed costs tend to be constant over a range of production or sales, and variable costs tend to change as production or sales volume fluctuates.
Some of the variable costs are direct materials, per unit packaging, transaction fees and commissions. Fixed costs can include rent, paid administrative staff and insurance premiums.
There are expenses that come in a fixed and variable. Consistently classify the costs to calculate the contribution margin more accurately.
Product Profitability Analysis
Product profitability analysis enables businesses to make comparisons between products, not just on sales revenue but on financial contribution. This may result in high sales for a product that still has relatively high variable costs.
Businesses can analyse the contribution margin per unit, total contribution margin, sales volume and contribution margin ratio to find better performing businesses. They also need to take inventory requirements, customer demand and capacity into account.
This can help make decisions regarding product, inventory, marketing and pricing. To understand how to determine product profitability, calculate each product’s contribution margin and compare the results with its sales volume.
Conclusion
Contribution margin is useful for businesses to identify how much each product contributes towards fixed expenses and profit. Using the contribution margin per unit, the ratio and sales volume analysis, businesses are better positioned to make informed pricing and product decisions.
Use contribution margin analysis, overall profit measures and customer demand to identify products that promote sustainable business growth.
Frequently Asked Questions
What is a good contribution margin?
The contribution margin varies from industry to industry, from model to model and from expense level to expense level. Calculate and compare margins of similar products and check if total contribution meets fixed costs.
Is contribution margin the same as profit?
No. Contribution margin simply deducts variable costs from sales, whereas profit deducts any additional costs, depending on the type of profit.
Can contribution margin be negative?
Yes. When a product has a negative contribution margin, its variable costs will be greater than the selling price. If more units were sold at that price, the losses would be greater before taking into account the fixed costs.
Why is contribution margin useful for small businesses?
It assists small businesses to compare products, analyze pricing, track cost changes and determine which products are most effective at covering the operating cost.
How often should businesses calculate contribution margin?
It can be viewed on a monthly basis or if there are major price changes or increases in supplier costs or sales volume. Regular review maintains product and price decisions are made with the latest information.