Insurance is an important expense for almost every business, but the price can vary widely depending on the company, industry, location, employees, and coverage needs. Before selecting a business insurance policy, it is important to have an understanding of business insurance costs so that you can realistically plan your budget without paying for insurance coverage that is not necessary.
Knowing what factors impact your premium can make planning your insurance easier, regardless of whether you’re an online company, a professional service, a small shop, or a contractor business.
How Much Does Small Business Insurance Cost?
The small business insurance cost depends on the type of coverage you purchase and the risks associated with your business. An insurance company with a couple of personnel and little tangible assets might have differing insurance needs than a construction firm that has significant equipment and employees.
Common factors that affect insurance costs for small business include:
- Type of business and industry
- Number of employees
- Location
- Annual revenue
- Claims history
- Coverage limits
- Deductibles
- Business property and equipment
- Services or products you provide
When you ask the question how much is small business insurance, the monthly cost is important, but not the only one of the considerations. A lower cost policy might not have as high of limits or as many protections and could leave your business vulnerable to some losses.
What Types of Coverage Affect Business Insurance Costs?
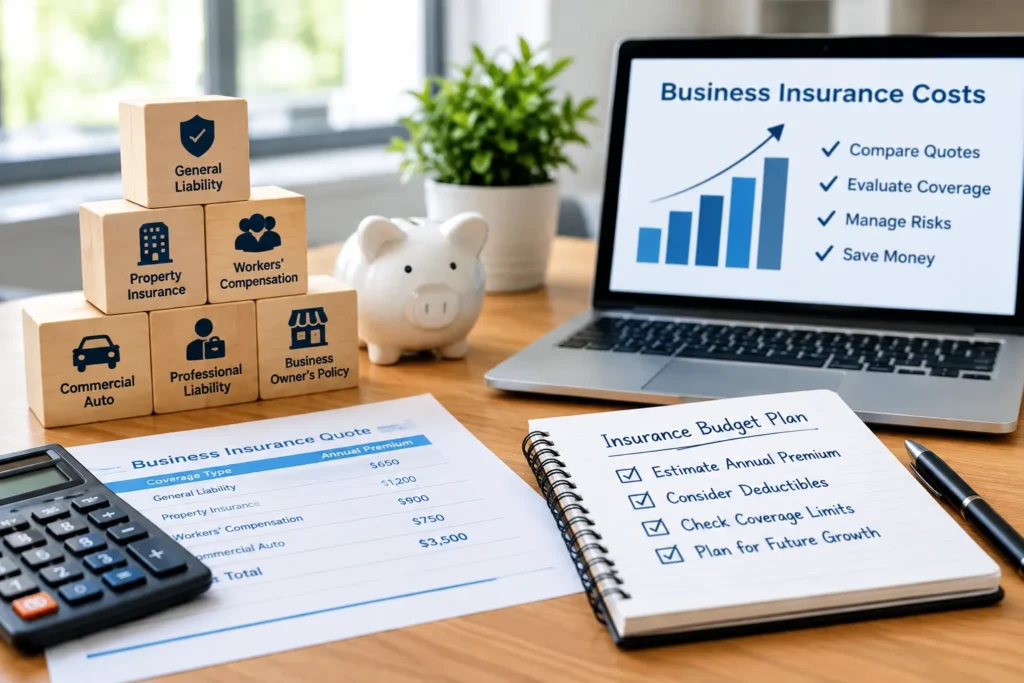
The type of insurance policies you have influences your insurance quotation. Typical business coverages are general liability, business owner’s policy, professional liability, commercial property, commercial auto, and workers’ compensation policies.
For instance, a company that has a business address but serves customers there has different liability exposure than a consultant that works out of the office and has no customer transactions occur there.
The company insurance cost can also rise if you increase your coverage limits, or if you have more vehicles, specialized equipment or extra coverage for specific business risks.
The aim is to ensure that coverage is equal to risks faced rather than merely the lowest premium.
Does an LLC Have Different Insurance Costs?
An LLC does not automatically determine your insurance price. LLC business insurance cost depends more on the company’s industry, operations, location, revenue, employees, and coverage requirements.
An LLC may offer some legal protections, but business insurance is not the same. Your business may still be liable for claims of property damage, injuries, professional errors, or other covered perils.
For business owners, this is the reason why it’s important to think about insurance outside of your legal business structure.
How Can You Budget for Business Insurance?
If you’re unsure, you should first determine the coverage your business requires and then get quotes for coverage of the same amount. This will help you determine the amount you should expect to spend every year.
This will then allow you to factor insurance into your business expenses. Look at the annual premium, deductibles, policy limits and any extra coverage you might need for your business rather than just at the monthly premium.
You can also use this as a tool to walk through your policy on an annual basis. Your coverage needs and premium may change due to changes in revenue, number of employees, equipment, locations, and/or services.
How Can You Save Money on Business Insurance?
There are several ways to manage small business insurance prices without simply reducing necessary coverage.
One option is to compare quotes from multiple insurers. You can also ask whether bundling certain policies could reduce your overall premium.
Other ways to potentially reduce business insurance costs include:
- Maintaining a strong safety program
- Reviewing coverage limits regularly
- Choosing an appropriate deductible
- Avoiding unnecessary duplicate coverage
- Improving workplace security
- Keeping a clean claims history
- Asking about available discounts
- Comparing policies during renewal
If you are wondering how to save money on business insurance, it is important to manage risk instead of sticking with the most affordable. If your business is not covered for some of the important risks, then you may not want to save money on your premiums.
What Should You Consider Before Choosing a Policy?
The price is not the only criteria. When buying coverage, check the terms of the policy, what is covered and what is not, the limits, deductible and claim process.
Discuss if the policy is in line with your current business operations. An existing policy may not offer the coverage you’re looking for if your business expands or evolves.
Knowing the cost of insurance for a small business is thus just the beginning. The policy needs to be cost-effective and provide some protection to the company’s real risks.
Frequently Asked Questions
How much is small business insurance?
The price varies based on the business type, location, revenue, employees, claims history, coverage limits, and types of insurance purchased.
What is the average small business insurance cost?
There is no single price that applies to every business. Insurers calculate premiums based on the company’s specific risks and coverage needs.
What affects company insurance cost?
Industry, location, revenue, employees, claims history, property, vehicles, coverage limits, and the type of work performed can all affect the cost.
Is LLC business insurance cost different from other businesses?
Not necessarily. Being an LLC does not automatically determine the premium. The business’s operations and insurance needs are more important factors.
How can I lower my business insurance costs?
Compare quotes, maintain good safety practices, choose appropriate deductibles, review coverage regularly, and ask insurers about available discounts.
Are small business insurance prices the same for every industry?
No. Different industries have different risks, so insurance premiums can vary significantly between businesses.
Do all small businesses need insurance?
Insurance requirements vary by location, industry, contracts, and business activities. Some coverage may also be required by law, such as workers’ compensation in applicable situations.
Does a higher deductible lower insurance costs?
A higher deductible may reduce your premium, but it also means your business would pay more out of pocket when a covered claim occurs.
Should I choose the cheapest business insurance policy?
Not necessarily. Compare coverage, exclusions, limits, deductibles, and insurer service along with the premium before making a decision.
How often should I review my business insurance?
Review your coverage at least annually and whenever your business adds employees, locations, equipment, vehicles, services, or significantly changes its revenue.